The first insurance estimate arrives. It looks detailed. The contractor reviews it and finds gaps—missing drip edge, incomplete ice-and-water coverage, no allowance for decking, underpriced labor, or code-required items that were never listed. The difference between that estimate and the actual cost of a proper restoration is often several thousand dollars. The mechanism for closing the gap is called a supplement.
A supplement is not a complaint, a threat, or an attempt to inflate the claim. It is a formal, itemized request that asks the carrier to revise the approved scope so it matches the work required to restore the property. Experienced storm contractors treat supplements as a standard part of the process. Contractors who ignore them either absorb the shortfall, pressure the homeowner to pay the difference, or quietly reduce the quality of the work so the job stays within the original number.
Why Initial Estimates Routinely Fall Short
Adjusters work under time pressure and with limited access. Many inspections are conducted from the ground or with only brief roof time. Estimating software applies average prices and standard assumptions. Complex roofs, steep slopes, multiple penetrations, and local code details are easy to under-count or omit entirely.
Common omissions include:
Drip edge at eaves and rakes
Adequate ice-and-water membrane at eaves and valleys
Starter strips and proper ridge cap
Accurate quantities of flashing at walls and penetrations
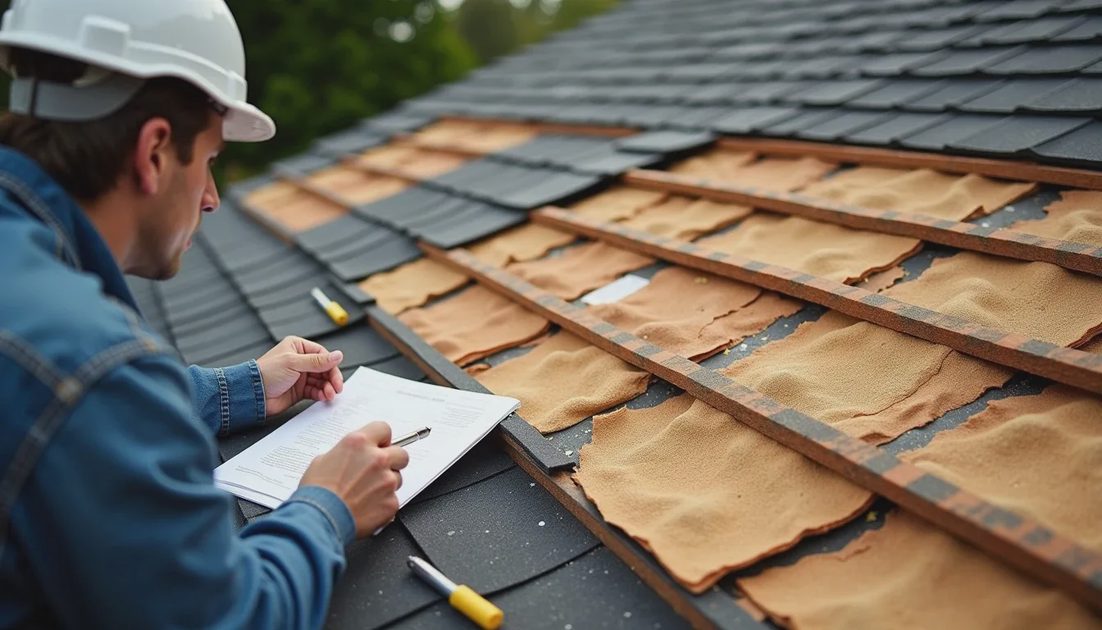
Decking replacement once the old covering is removed
Code-driven ventilation or fastening upgrades
Overhead and profit when multiple trades are coordinated
Disposal and site-protection costs
None of these items are exotic. Most are required for a code-compliant, warrantable roof. When they are missing from the first estimate, the job is underfunded from the start.
How a Supplement Actually Works
The process is straightforward when handled correctly.
Identification of Gaps
The contractor compares the carrier’s estimate line by line with the actual scope required. Measurements, photographs, manufacturer specifications, and local code references support each difference.
Documentation Package
A clear supplement package usually contains:
A revised or annotated estimate showing the added or corrected line items
Photographs that justify each addition (especially for hidden conditions found during tear-off)
Brief written explanations tied to code, manufacturer requirements, or visible damage
Quantity calculations that can be verified
Submission and Review
The package is submitted to the carrier’s desk adjuster or supplement team. Many carriers expect supplements and have processes designed to review them. Well-documented requests are frequently approved in whole or in large part. Poorly documented or speculative requests are more likely to be reduced or denied.
Timing
Some supplements are identified before work begins. Others arise only after tear-off reveals soft decking or deteriorated flashing that could not be seen earlier. Both are legitimate. The key is prompt documentation so the carrier can respond while the evidence is still clear.
Why Good Contractors Insist on the Process
A contractor who absorbs consistent shortfalls either loses money on every storm job or compensates by thinning materials, skipping details, or rushing labor. None of those outcomes serve the homeowner. A contractor who systematically supplements protects the integrity of the scope and keeps the financial structure of the job aligned with the actual work.
For the homeowner the benefit is direct. Legitimate items that belong in the claim are funded by the policy rather than by an unexpected out-of-pocket bill or by a reduction in quality. The finished roof is more likely to meet code, carry a valid manufacturer warranty, and perform for its expected life.
Ignoring a shortfall does not make the missing work unnecessary. It only decides who pays for it or whether it gets done at all.
What Homeowners Should Expect and Request
Ask the contractor early how they handle differences between the insurance estimate and the required scope. A clear answer usually includes:
A line-by-line review of the carrier’s estimate
Identification of missing or underpriced items
A willingness to prepare and submit a documented supplement
Communication with you about what is being requested and why
Be wary of contractors who dismiss the insurance number entirely and simply demand the full difference from you, or who promise to “make it work” without ever addressing the gaps. Both approaches transfer risk onto the homeowner.
During the work, if hidden damage is found, expect the contractor to photograph it, quantify it, and submit a timely supplement rather than presenting you with a surprise invoice and no supporting claim activity.
Realistic Outcomes
Not every requested line item is approved. Carriers may challenge quantities, pricing, or the necessity of certain upgrades. A professional supplement still improves the final number in the large majority of cases. Industry experience consistently shows that documented supplements recover meaningful additional funds on a high percentage of storm roof claims—often in the range of several thousand dollars on a typical residential replacement.
The alternative—proceeding on an incomplete estimate—leaves the shortfall to be covered by the homeowner, by reduced scope, or by the contractor’s margin. None of those options produce a better roof.
Practical Path Forward
Treat the first insurance estimate as a starting document, not a final scope. Expect a competent storm contractor to review it against the real requirements of the job and to pursue legitimate missing items through the supplement process. Ask how that review will be handled and how you will be kept informed.
A supplement is one of the ordinary mechanisms that keep storm claims accurate. Contractors who use it properly are protecting the work and the homeowner. Contractors who ignore it are accepting an underfunded job and transferring the consequences downstream. In storm restoration, that difference shows up in the quality and completeness of the finished system.